
FT Partners Quarterly InsurTech Insights and Annual Almanac
Report Features:
Q2 2026 and historical InsurTech financing and M&A volume and deal count statistics
Largest InsurTech financings and M&A transactions in Q2 2026
Most active InsurTech investors
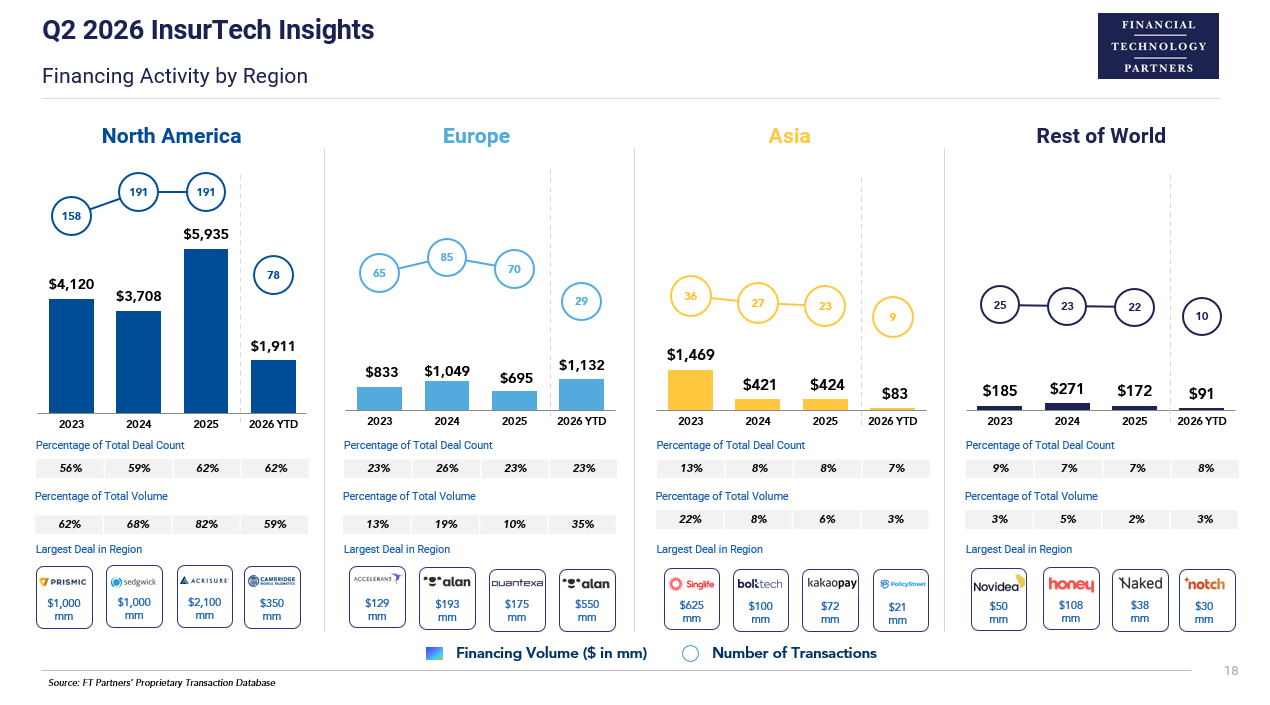
Breakdowns by geography, product type and business model
Corporate VC activity and strategic investor participation
Other industry, capital raising and M&A trends in InsurTech
Key Highlights:
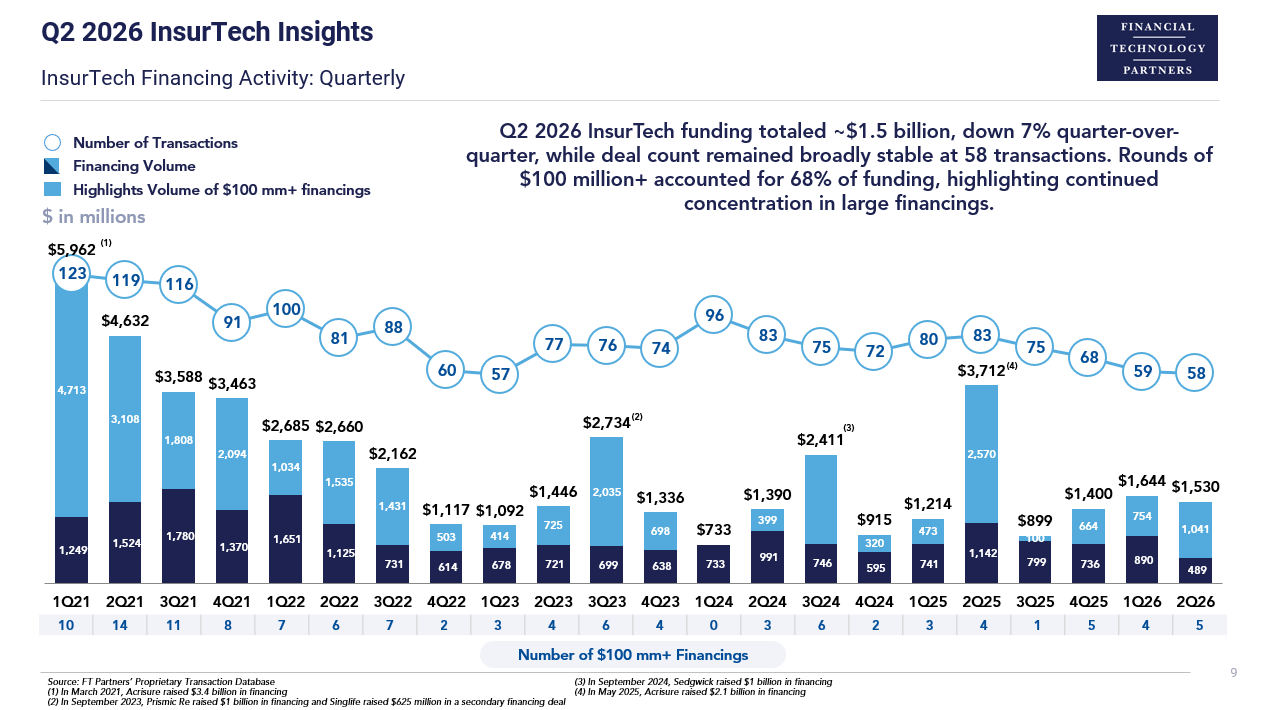
InsurTech financing volume totaled approximately $1.5 billion in Q2 2026, down 59% year-over-year and 7% sequentially. H1 funding reached approximately $3.2 billion, with annualized volume tracking below 2025 but above 2024.
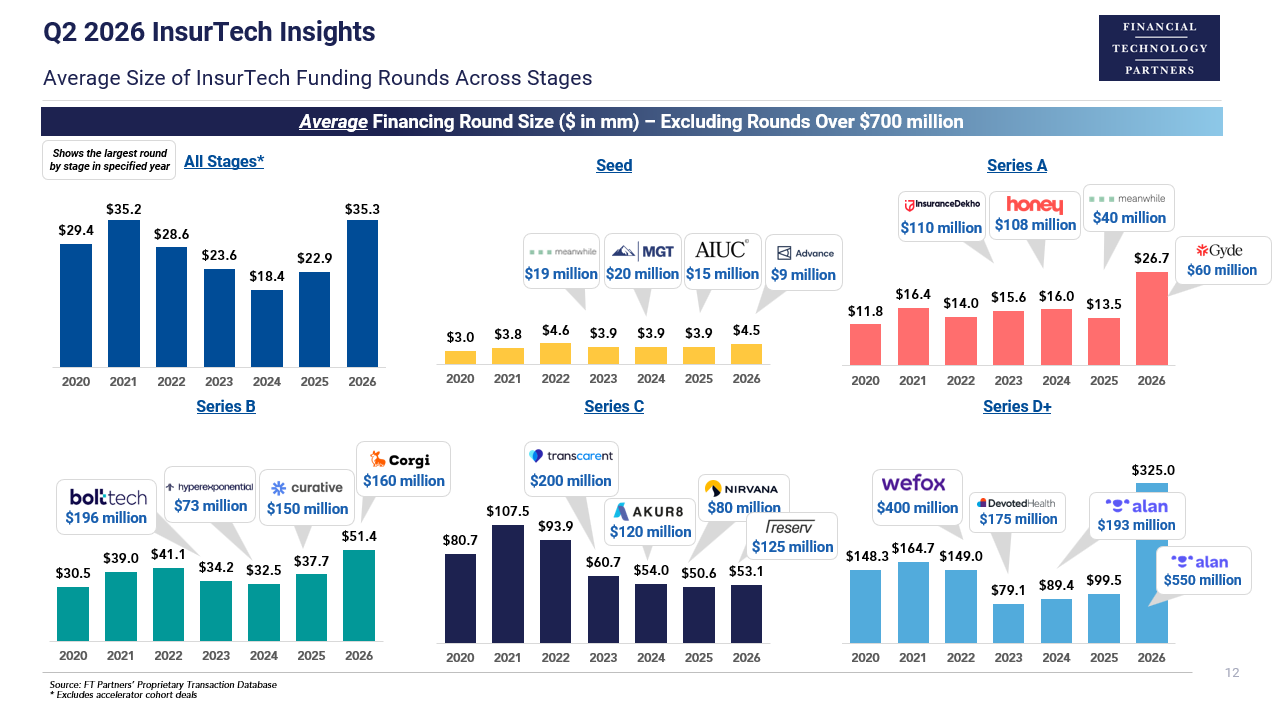
Despite lower overall funding, InsurTech Series A rounds reached a record average size of nearly $27 million in 2026, compared with $13.5 million in 2025. Q2 also saw five $100 million+ capital raises across Alan, Corgi, Reserv and Chapter, including two separate rounds for Corgi.
AI-native companies accounted for 47% of InsurTech financings in H1 2026, up from 45% in full-year 2025, with notable raises by Cambridge Mobile Telematics, Corgi and Lassie. Corporate or strategic investors led 42% of financing rounds, highlighting their continued participation in the sector.
InsurTech M&A totaled $1.4 billion in announced volume across 74 transactions in H1 2026, though only nine deals had disclosed values. Annualized deal count tracked below 2025 but broadly in line with 2024, with notable transactions involving MSA Mizar, Flock and TheGuarantors. IPO activity remained relatively quiet in Q2 2026, while Tigerless Health announced a planned SPAC merger valuing the company at approximately $280 million.
View More Reports